How we picked the markets
We screened metro areas on four measures: the ratio of median rent to median purchase price, the breadth of local employment, the pipeline of new rental supply and the direction of insurance and property taxes. A city can look cheap and still be a poor bet if one employer dominates or if insurance has doubled in three years.
We deliberately left out markets where prices have run far ahead of local incomes. Those places can still reward a long-term owner who knows a specific street, but they are not where a new investor should start. The real estate section has the buying and selling guides that sit behind this ranking, and our renovation hub covers the repair math before you make an offer.
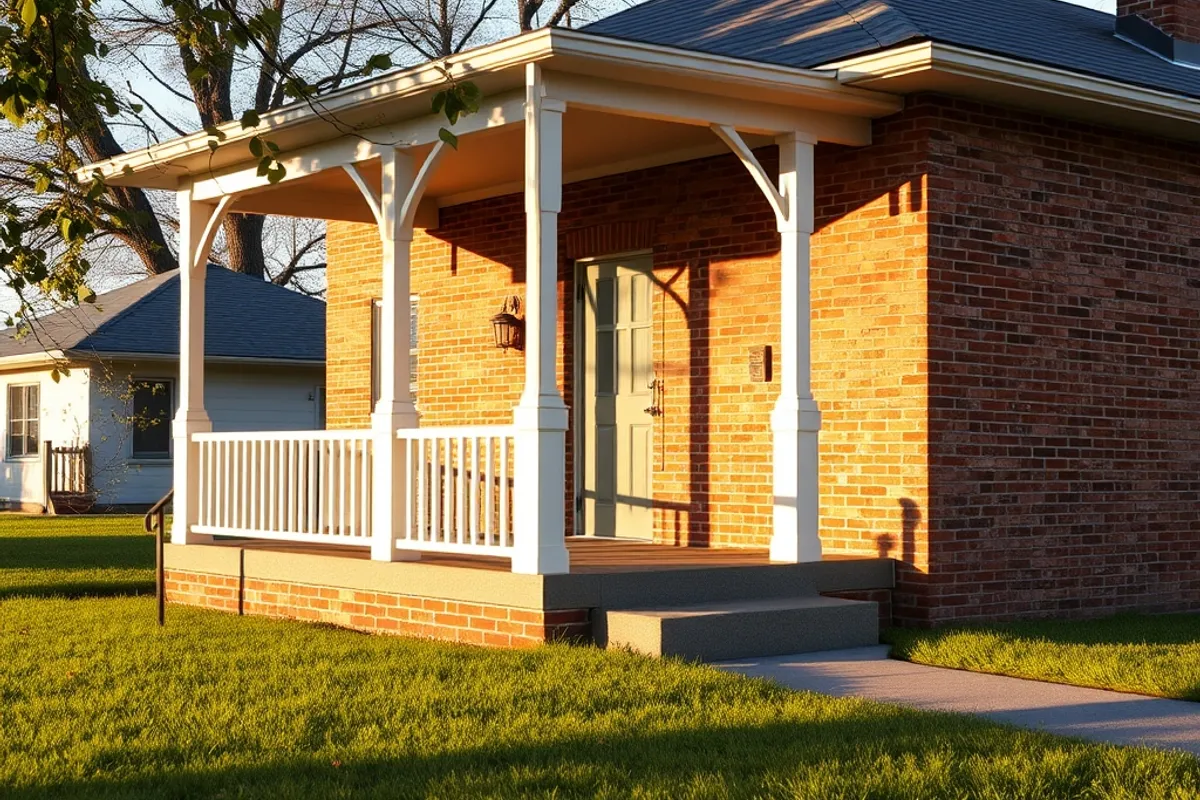
Kansas City: steady jobs, modest prices
Kansas City keeps appearing on sensible investor lists because it has a broad employment base in logistics, health care and finance, and purchase prices that still allow a rent-to-price ratio near the healthy range. The trade-off is slow appreciation. This is a cash-flow market, not a flip market.
Look at older brick homes near established retail rather than new builds on the edge of the metro. Insurance is manageable compared with storm-prone coastal cities, but property taxes vary sharply by county. Run the numbers with the actual tax bill, not the seller's estimate. A house that cash-flows at a 6.5 percent cap rate can turn negative if the tax assessment jumps after sale.
Columbus: a deep rental base
Columbus has universities, hospitals, insurance companies and a growing logistics sector, which produces a steady stream of renters who stay for a few years rather than a few weeks. That matters for turnover costs. The city also has a wide range of housing stock, from small post-war houses to new suburban rentals.
The risk is oversupply in the new-build segment. Check the pipeline of apartments near any property you consider. A house that competes with a new amenity building needs a clear advantage, such as a yard or a garage. Focus on older neighbourhoods with limited land for new competition and easy access to a major employer.
A rental property is a business with a roof. The city is the location, but the deal is still decided by the numbers on your spreadsheet.
Greenville: lifestyle demand with a limit
Greenville has attracted remote workers and retirees, and that demand has pushed prices up. It still offers a reasonable balance for a small investor who buys a modest house near the city rather than a showpiece downtown. Rents are supported by a growing food and manufacturing base, and the climate keeps maintenance costs moderate.
The limit is income growth. Lifestyle demand can lift prices faster than local wages, which eventually squeezes rent growth. Be conservative about future rent increases. If the deal only works with 8 percent annual rent growth, it does not work. Buy for today's rent and treat growth as a bonus.
San Antonio: military, medical and tourism
San Antonio has a large military presence, a substantial medical sector and a tourism economy that supports short-term and long-term rentals. Prices remain lower than Austin, its neighbour to the north, which gives a new investor a better chance at positive cash flow. Property taxes are high, so the tax line deserves close attention.
Avoid buying purely on tourism projections. Short-term rental rules can change quickly at city level, and a property that only works as an Airbnb is a policy risk. A long-term rental near a hospital or base is less exciting and more durable. Check flood maps as well, because heavy rain has exposed drainage problems in parts of the metro.
Chattanooga and Boise: two different bets
Chattanooga offers a lower entry price, fibre broadband and a manufacturing base that has attracted new employers. It is a value bet with improving fundamentals. Boise is a growth bet: strong in-migration, limited buildable land in desirable areas and higher prices. Both can work, but they fail in different ways.
Chattanooga can suffer from thin resale demand if you need to sell quickly. Boise can suffer from insurance, wildfire risk and a market that cools when remote-work migration slows. Match the market to your holding period. If you may need the money in three years, the lower-volatility market is the safer choice, even if the headline yield is smaller.
The numbers that decide the deal
Ignore the online rent estimate until you have spoken to three local property managers. Then calculate with realistic vacancy, maintenance, insurance, taxes and management fees. A common mistake is using the mortgage payment as the only cost. A roof, a water heater and a turnover can wipe out a year of cash flow.
The Census Bureau's housing data is a useful starting point for vacancy and tenure trends, but the final decision belongs to a local spreadsheet. If the deal needs optimistic assumptions to clear, walk away. There will be another house, and the market does not pay you for being brave.